
Monday, September 7, 2026

U.S. Defense Contractors Hit 163% Revenue Growth as Global Military Spending Accelerates

Firefly Aerospace posted $159.9 million in 2025 revenue, up 163% year-over-year, as governments worldwide increase defense allocations. The U.S. aerospace firm projects another 172% jump in 2026, with 80% of revenue already contracted. Maritime surveillance systems captured $9.89 billion globally in 2025 as nations prioritize coastal defense.

LM Salvado
LM Salvado

March 22, 2026

U.S. Defense Contractors Hit 163% Revenue Growth as Global Military Spending Accelerates
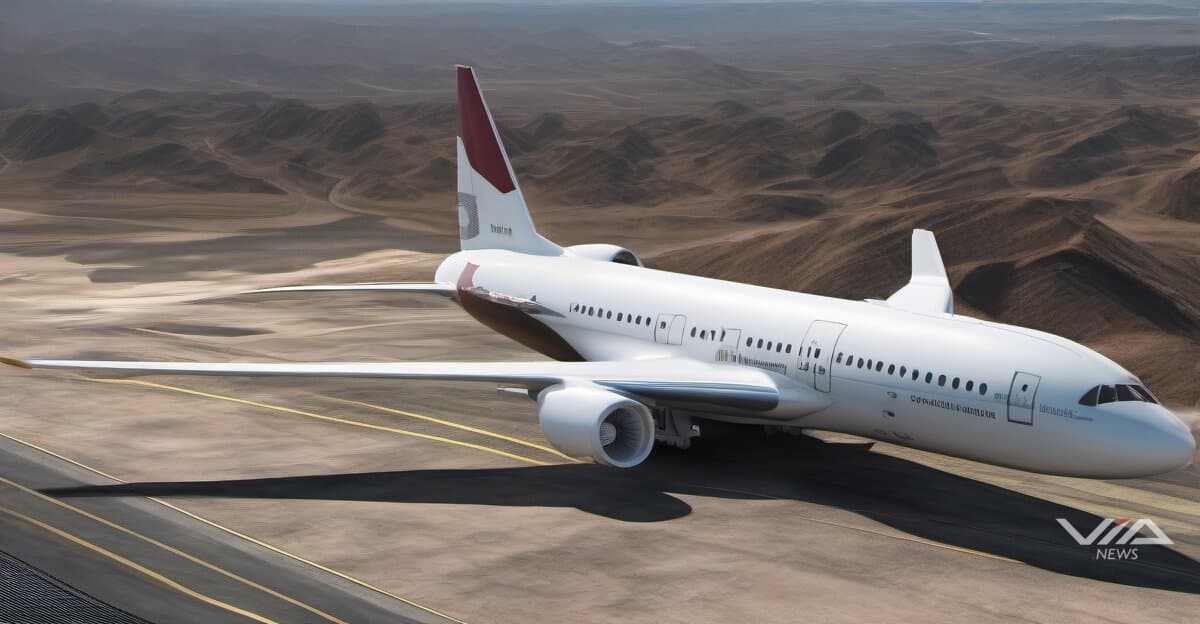
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

Firefly Aerospace generated $159.9 million in revenue for 2025, marking a 163% increase from the prior year as U.S. defense spending aligns with broader global military budget expansions across NATO allies and Asia-Pacific nations. The company's 2026 revenue guidance midpoint indicates another 172% year-over-year jump, with 80% of projected revenue already under contract.

Government spending on space infrastructure and national security systems is driving growth across Western and Asian defense markets. U.S. contractors are landing substantial awards, including Lockheed Martin's Navy sonar contract secured in February 2025, while European and Indo-Pacific nations accelerate procurement cycles.

Maritime security systems captured $9.89 billion globally in 2025, with surveillance and tracking platforms representing 31.48% of the market. This concentration reflects heightened government prioritization of naval capabilities from the South China Sea to the Baltic, where territorial tensions are reshaping defense procurement strategies.

Strategic acquisitions are accelerating sector consolidation internationally. The SciTec acquisition was characterized as highly strategic for national security and defense applications, mirroring consolidation patterns among European defense contractors and Asian aerospace firms. Companies are positioning themselves to capture specialized contracts requiring advanced technical capabilities across multiple theaters.

Firefly's 80% pre-booked revenue for 2026 suggests multi-year contract structures common in defense procurement worldwide. This forward revenue coverage provides unusual clarity compared to commercial aerospace sectors still recovering from pandemic-era disruptions.

Defense budget allocations increasingly favor space-based systems and integrated surveillance technologies across NATO members, Japan, South Korea, and Australia. The shift from traditional hardware to combined space, maritime, and terrestrial systems is reshaping contractor revenue profiles globally.

The revenue acceleration spans both established U.S. defense primes and emerging space contractors, suggesting structural expansion in Western defense spending rather than isolated program success. This trend parallels increased military budgets across allied nations responding to geopolitical pressures.
In this story · Knowledge Files

About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Network, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
AI Investment Boom Meets Market Skepticism: Palantir's Contract Win vs. Stock Slide Amid Record Private AI Funding
Palantir secured the Army's high-profile TITAN AI-sensing contract and added a new executive, yet its stock fell 6% the same day — a sign that even marquee government AI wins no longer guarantee investor confidence. This tension plays out against a backdrop of surging private capital flooding into AI and AI-adjacent companies (Stability AI, Socure, Generalist AI, Emerald AI, and others), showing a bifurcated market: venture funding for AI remains red-hot while public-market sentiment toward AI-defense/enterprise plays is growing more cautious.
Our read on the data ›
Signals we're tracking
Satellite-Terrestrial Network Integration Acceleration
Increased investment and launches in hybrid satellite-cellular networks across telecom industry; competitive responses from other carriers; regulatory activity around satellite spectrum; expansion of emergency/rural connectivity use cases
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
Checked against the original source
4,981
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,981 facts checked against source5,278 source documents archived
Query this data → isubstrate.com