
Saturday, October 24, 2026

Oil Breaks $100 as Hormuz Crisis Disrupts Global Bond Markets and Safe-Haven Flows

Oil surged past $100 per barrel on April 14 after Trump threatened a Strait of Hormuz blockade following collapsed US-Iran negotiations, triggering violent swings in Treasury yields worldwide. The dollar strengthened on safe-haven demand despite commodity price spikes, while central banks from Ottawa to Washington face conflicting pressures between inflation control and geopolitical supply shocks. Global investors confront a rare regime where traditional portfolio diversification strategies—Trea

LM Salvado
LM Salvado

April 15, 2026

Source Trace Score3 source documents3 with a live linkVerifiability: Strong
Oil Breaks $100 as Hormuz Crisis Disrupts Global Bond Markets and Safe-Haven Flows
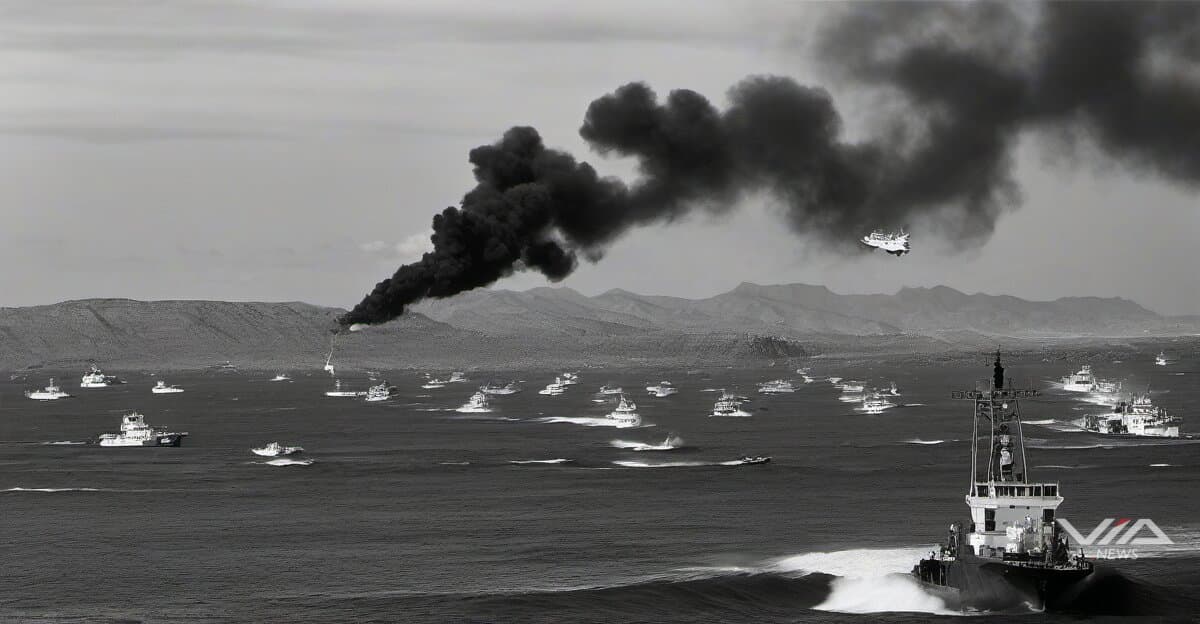
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

Oil prices surged past $100 per barrel on April 14 following Trump's threatened blockade of the Strait of Hormuz after US-Iran negotiations collapsed, creating sharp dislocations across global bond and currency markets.1 The crisis hits as central banks from North America to Europe maintain restrictive monetary policy, complicating responses to supply-driven inflation shocks.

Treasury yields swung violently as safe-haven demand collided with inflation concerns from the energy price spike. The dollar strengthened despite rising commodity prices—an unusual dynamic that typically sees dollar weakness during energy rallies.2 This reflects uncertainty among international investors about whether geopolitical risk or inflation concerns should drive positioning.

The Bank of Canada held its policy rate at 2.25% as Federal Reserve officials prepared monetary policy testimony, creating a challenging backdrop for fixed-income investors across North American markets.3 Canadian consumer debt pressures have mounted amid economic uncertainty, mirroring strains in other developed economies facing restrictive monetary conditions.

The crisis forces a choice between two historically reliable responses common to investors worldwide: moving into dollar-denominated Treasuries for safety, or rotating into commodities as inflation hedges. The simultaneous demand for both asset classes creates cross-currents that undermine traditional portfolio diversification strategies used by pension funds and sovereign wealth managers globally.

Major US stock indices initially fell sharply before trimming losses, with the Dow, S&P 500, and Nasdaq all recovering partially from morning declines.1 The recovery suggests global investors remain uncertain whether the geopolitical shock will prove transitory or mark a regime shift requiring portfolio repositioning across international markets.

Central banks worldwide face compounded challenges. Restrictive policy rates designed to contain inflation now confront a supply shock that could reignite price pressures while simultaneously threatening growth. The Bank of Canada's 2.25% rate and Federal Reserve's current stance were calibrated for demand-driven inflation, not energy supply disruptions affecting global trade routes.

Currency markets reflect this uncertainty, with traditional safe-haven flows supporting the dollar even as commodity-linked currencies from Australia to Canada face pressure from both the oil spike and risk-off sentiment. The foreign exchange volatility complicates international capital flows and cross-border investment decisions.

The coming weeks will test whether central banks maintain current policy paths or acknowledge that geopolitical supply shocks require different responses than demand-driven inflation. Bond market pricing suggests investors expect volatility to persist until policy clarity emerges from major monetary authorities.

Source documents

Via News is a conduit. We point to the source documents behind this report — we don't replace them. Trace any claim to its source and decide what to trust. How we source

Source Trace Score3 source documents3 with a live linkVerifiability: Strong
  1. [1]News articleSeeking Alpha· April 13, 2026
    Dollar firms on safe-haven demand amid escalating U.S.-Iran tensions: Currency Recap
  2. [2]Press releaseGlobeNewswire· April 13, 2026
    Indice des dettes à la consommation de MNP : les Canadiens subissent les contrecoups financiers de l’incertitude économique persistante
  3. [3]News articleYahoo Finance· April 13, 2026
    Stock market today: Dow, S&P 500, Nasdaq trim losses after Trump orders Hormuz blockade against Iran

In this story · Knowledge Files

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Enterprise Software Races to Govern and Consolidate Around Agentic AI
Enterprise software vendors are repositioning around autonomous AI agents. Salesforce is acquiring Braze, ServiceNow is launching agent governance tools (AI Passport, Super Intelligence Control Tower), SAP is pushing its 'Autonomous Enterprise', and Zeta is launching AthenaOS and its own inference model. Palantir is embedding itself in banking, aviation and sovereign AI infrastructure through partnerships with Customers Bank, Surf Air, Ondas and Armada. Governance, data sovereignty and enforced policy are emerging as preconditions for regulated sectors like finance. Investors such as Norwest see room to disrupt ERP and finance software, and they caution that AI should not be trusted with financial calculations. Consolidation and shareholder disputes (Salesforce/Braze, Tiny/Oso Cloud, ZenaTech/Boardwalktech) show the market reshaping.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,994
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,994 facts checked against source5,484 source documents archived
Query this data → isubstrate.com