
Thursday, October 15, 2026

Tesla Valuation Debate Exposes Global Divide Between Auto Metrics and AI Premium Pricing

UBS upgraded Tesla, acknowledging the stock reflects both near-term EV challenges and long-term AI bets. The move highlights a widening split among global analysts over whether to value Tesla as an automaker or technology company. Volatility patterns now resemble high-growth tech stocks rather than traditional manufacturers.

LM Salvado
LM Salvado

April 21, 2026

Tesla Valuation Debate Exposes Global Divide Between Auto Metrics and AI Premium Pricing
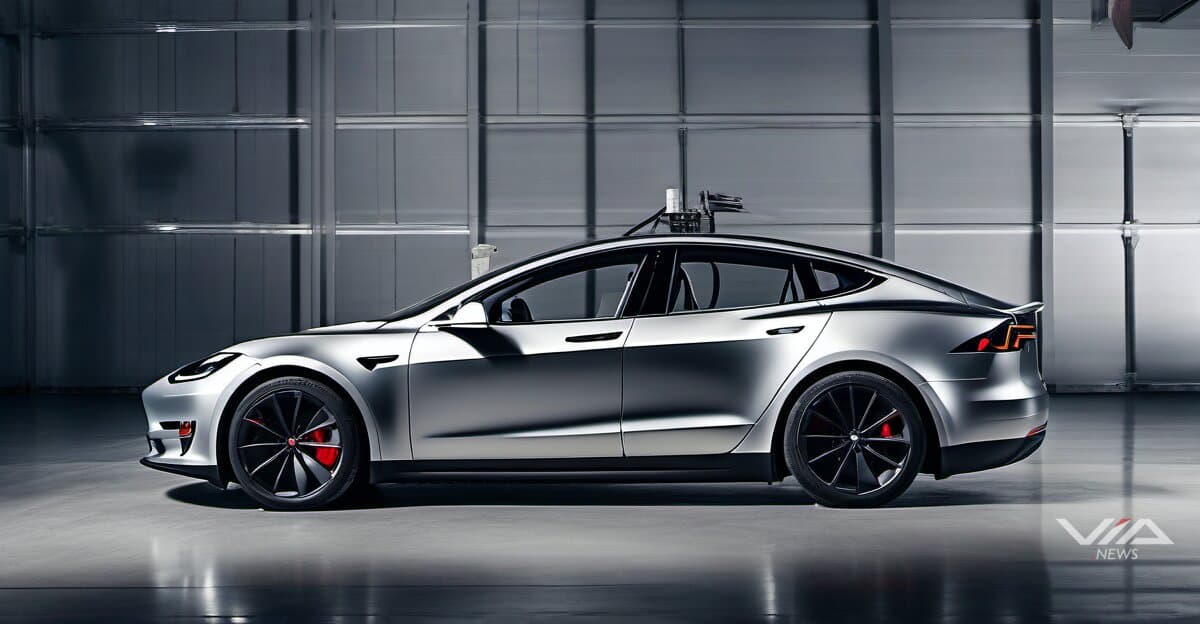
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

UBS upgraded Tesla and raised its price target, stating the valuation now better reflects the balance between immediate EV demand challenges and long-term opportunities.1 The revision signals growing institutional acceptance of Tesla's dual nature across global markets, where analysts remain split on fundamental valuation frameworks.

Joseph Spak maintains Tesla stock trades more on sentiment, narrative, and momentum than fundamentals.1 This divergence is pronounced internationally—European analysts typically apply traditional auto multiples while Asian tech-focused researchers incorporate software and AI revenue potential that remains unrealized.

The competing frameworks create persistent global valuation gaps. Traditional auto analysts use EV/Sales multiples common among manufacturers worldwide, while technology researchers price in autonomous vehicle commercialization and robotics deployment across multiple markets. Tesla's current premium suggests investors are betting on AI applications beyond core automotive earnings.

Markets worldwide react more strongly to FSD and AI announcements than quarterly delivery numbers. Each Full Self-Driving update or robotics demonstration drives stock movement independent of vehicle production data, reinforcing that Tesla's valuation incorporates substantial non-automotive optionality.

UBS's upgrade acknowledges near-term EV headwinds affecting global markets while validating long-term AI bets.1 Spak's momentum-based framework explains why Tesla exhibits volatility patterns closer to high-growth technology stocks than established automakers—a phenomenon visible across exchanges from New York to Frankfurt to Hong Kong.1

The tension between delivery-focused quarters and technology milestones continues to define Tesla's global market positioning. As autonomous and robotics revenue streams remain speculative, the valuation premium depends on investor willingness to price optionality over current automotive fundamentals.
In this story · Knowledge Files

About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Q4 2026 Clinical Catalyst Season: Big-Pharma Data Flow, Regulatory Milestones, and a Thin AI-Drug Fringe
October 2026 conferences (EASD, IGCS, NACFC, HFSA) are producing a dense run of late-stage readouts from Novo Nordisk, Lilly, Roche, Bayer, Vertex and Galderma. Regulatory milestones are scheduled behind them: the ivonescimab BLA PDUFA date on 2026-11-14, FDA acceptance of Roche's vamikibart BLA, and Scholar Rock's EMA resubmission. The AI-and-finance angle is peripheral. It consists of the AI-designed drug Rentosertib and QAIAx, a speculative microcap whose trial claims (the QIII pilot, anticipated 2027-01-01, and a patent update) are forecasts and filings rather than data, so they warrant skepticism.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,986
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,986 facts checked against source5,375 source documents archived
Query this data → isubstrate.com