
Sunday, September 20, 2026

$500B–$700B AI Infrastructure Bet Puts Global Supply Chains at Systemic Risk

Hyperscalers worldwide are set to deploy $500B–$700B in AI infrastructure in 2026 — one of the largest synchronized capital cycles in tech history. The bet assumes enterprise AI adoption accelerates fast enough to monetize a decade of fixed costs. If adoption stalls, write-downs will ripple from chip fabs in Asia to data center REITs across three continents.

LM Salvado
LM Salvado

May 21, 2026

$500B–$700B AI Infrastructure Bet Puts Global Supply Chains at Systemic Risk
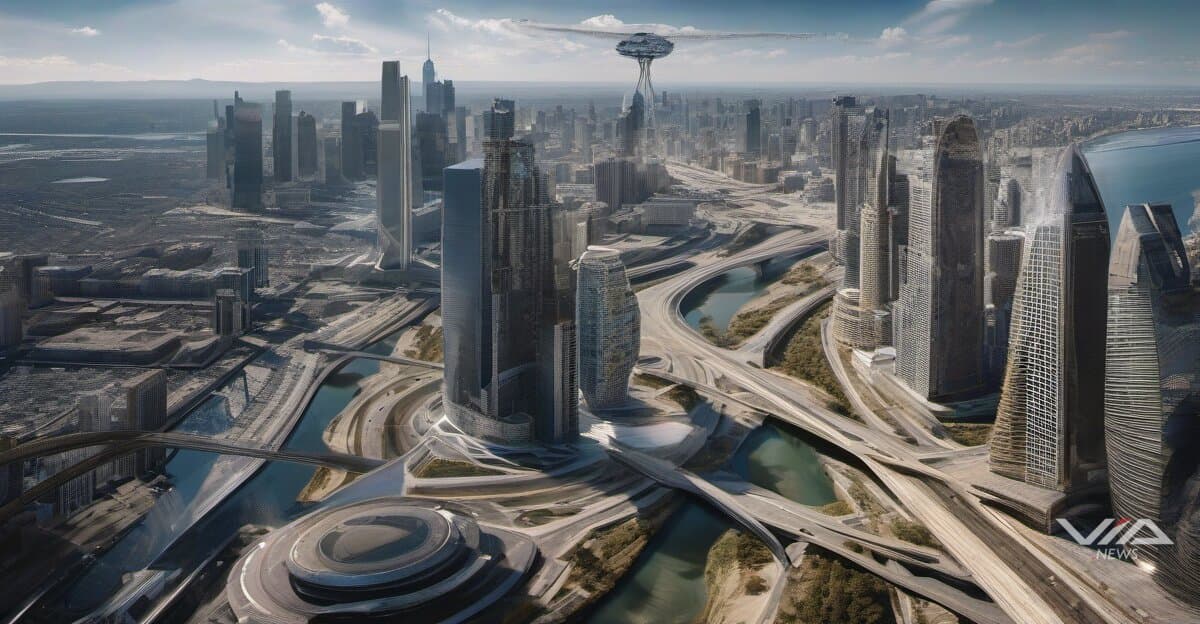
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

billions to billions in AI infrastructure spending is projected globally for 2026 — a synchronized capital deployment with no modern parallel.1 The entire bet rests on one assumption: enterprise AI workloads will scale before the debt does.

That assumption is fragile. Hyperscalers in the US, Europe, and Asia are commissioning power chips, networking gear, and GPU clusters months before customer demand fills the capacity.1 Fixed costs begin accruing on day one. Revenue follows — if it follows at all.

The risk is rated catastrophic in severity.1 The structural gap between infrastructure going live and infrastructure generating returns is not a planning error. It is baked into the model. The question is how wide the gap gets.

Stranded assets are the worst-case outcome. Data centers built for AI workloads that never materialize become write-down candidates.1 At this scale, write-downs would compress capital available for the next spending cycle — slowing AI momentum across the industry globally.

Power infrastructure is the physical constraint. AI data centers consume 5–10x more power per rack than conventional compute. Grid capacity, permitting delays, and energy costs vary sharply by region — from stressed grids in Western Europe to coal-dependent supply in parts of Southeast Asia. Underutilized infrastructure keeps drawing power regardless of utilization.

Supply chain exposure extends far upstream. ON Semiconductor's role supplying power management chips to major hyperscalers illustrates how orders placed today reflect capacity plans through 2027 and beyond.1 If those plans prove optimistic, cancellation risk flows back through semiconductor fabs, many concentrated in Taiwan and South Korea.

The systemic risk is what distinguishes this cycle from ordinary corporate overbuilding. Multiple hyperscalers — US-headquartered but operating globally — are deploying on overlapping timelines. A correction does not stay on one balance sheet. Pullbacks hit semiconductor suppliers, data center REITs, power equipment manufacturers, and fiber networks simultaneously, across markets from Frankfurt to Singapore.

billions–billions deployed in a single year must be monetized over a decade to justify the spend.1 The math holds if enterprise adoption curves steepen through 2027 and 2028. It breaks down if adoption plateaus while fixed infrastructure costs keep accumulating. The window to prove the cycle is narrower than the buildout timelines suggest.
About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Network, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
AI Boom Hits a Fork: Slowdown Calls Clash with Capex Confidence as Markets Get Nervous
Dario Amodei's repeated calls for a global slowdown in frontier AI development, echoed by Microsoft's new humanist AI code of conduct and FTC antitrust caution, are being publicly rejected by Nvidia and Meta leadership even as hyperscaler spending draws fresh skeptical scrutiny (Wachter's analysis, Burry-style overbuilding worries) and weak guidance from Adobe and a post-slowdown-comment selloff in GE Vernova signal investor jitters. Meanwhile wealth and security effects of the AI race keep compounding — Zhang Yiming's fortune surging on AI-driven ByteDance value, a Chinese hacking firm weaponizing AI against stolen government secrets, and low-quality AI-generated products (an AI sitcom, a spam-flooding agent platform) fueling backlash even as adoption races ahead.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
Berkshire Hathaway
Both facts report Berkshire Hathaway's cash position on 2026-01-01 with identical observation timestamps, but claim vastly different values: 380 billion USD vs 400 USD. These cannot both be true for the same entity at the same point in time. The magnitude of the discrepancy (a factor of ~10^9) rules out rounding, unit conversion, or methodological differences.
We flag conflicts openly ›
Recently verified
Checked against the original source
4,982
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,982 facts checked against source5,299 source documents archived
Query this data → isubstrate.com
$500B–$700B AI Infrastructure Bet Puts Global Supply Chains at Systemic Risk | Via News