
Monday, November 2, 2026

Why the AI Funding Surge Isn't a Bubble — It's Insurance

Three companies raised $156B in February 2026 — 83% of all global VC that month. While markets compare it to 1999, the structural reality tells a different story.

LM Salvado
LM Salvado

March 26, 2026

Why the AI Funding Surge Isn't a Bubble — It's Insurance
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

Everyone says AI is in a bubble. Some compare it to 1999. They're not entirely wrong. Compressed deal timelines, detached valuations, euphoric narratives. It rhymes, as they say.

But the DotCom bubble had no geopolitical skeleton. This one does.

In February 2026 alone:

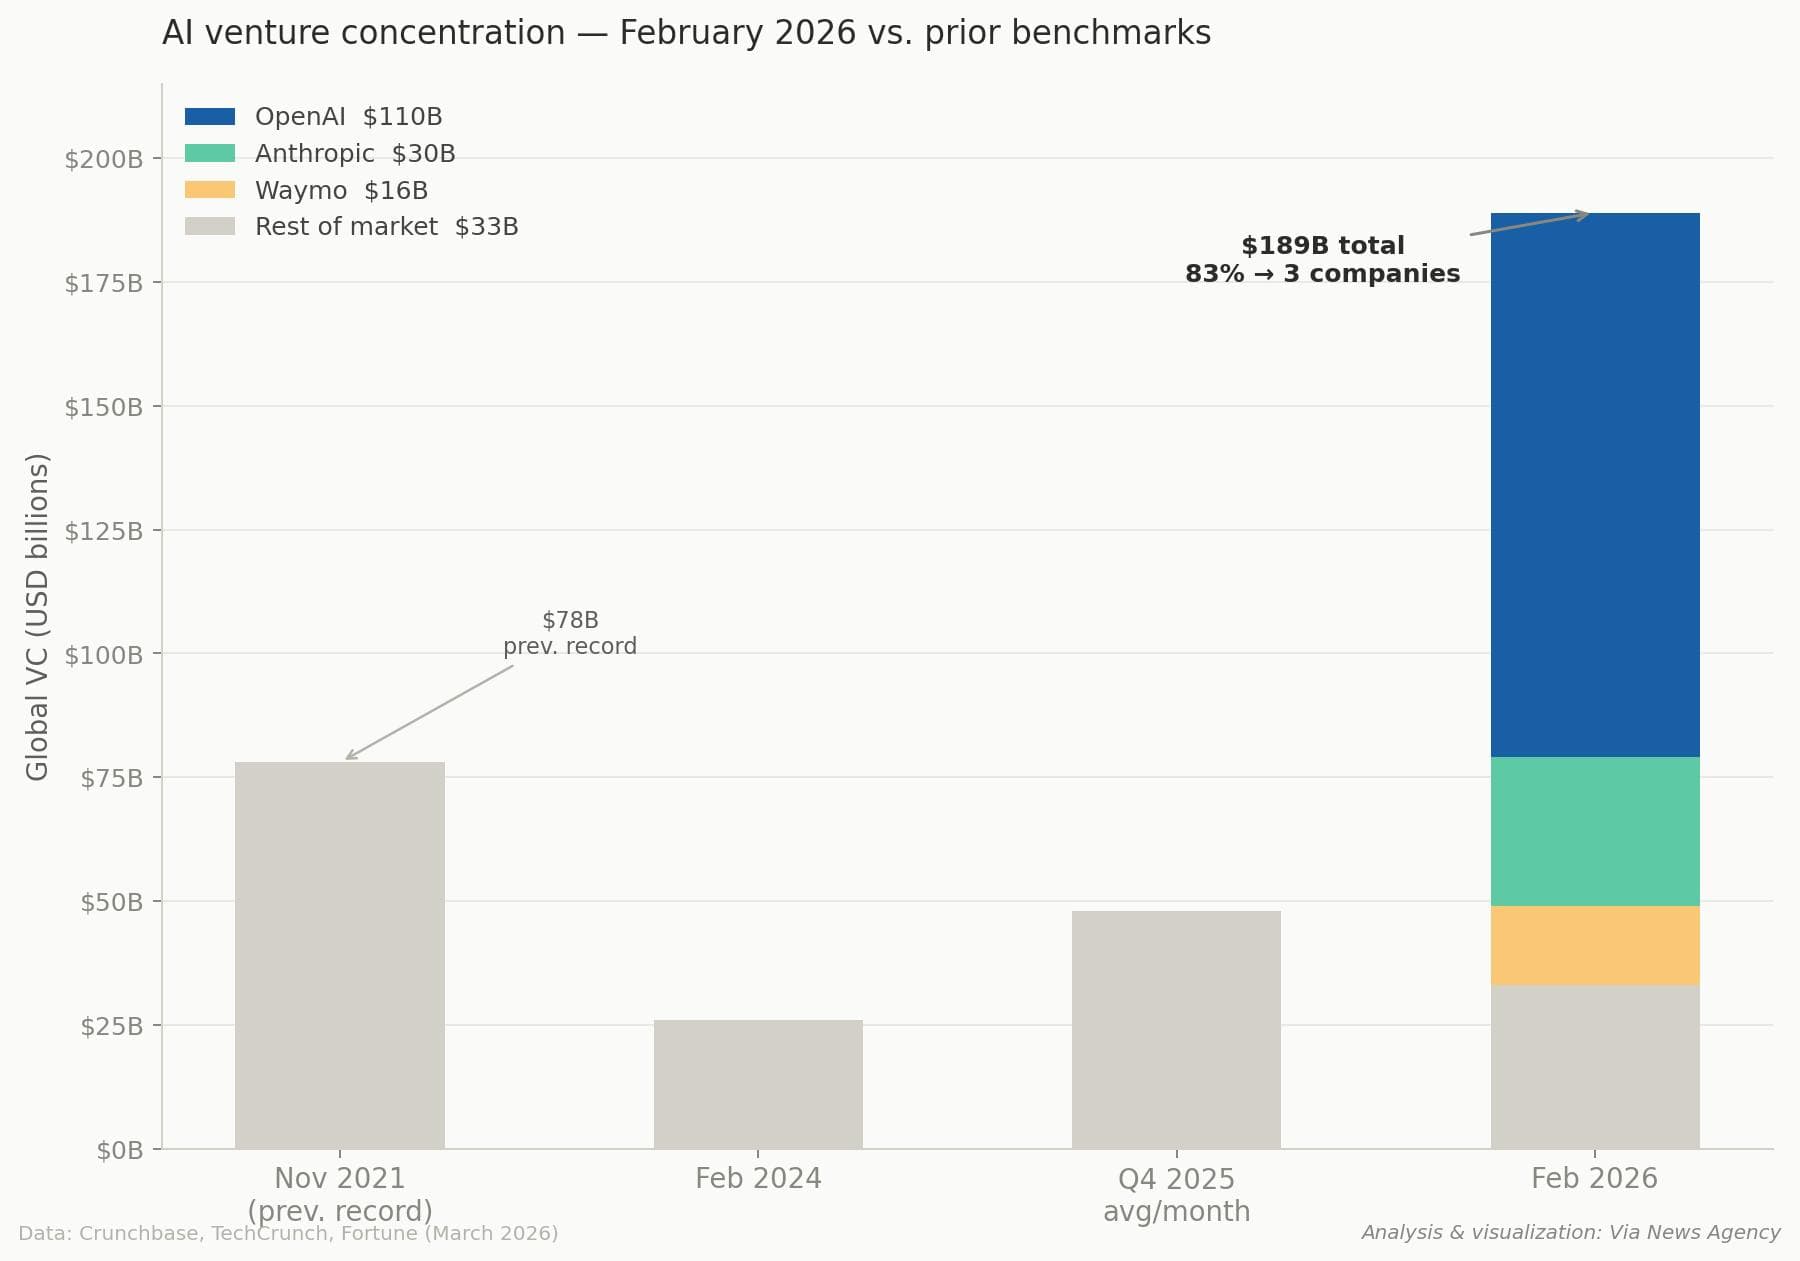
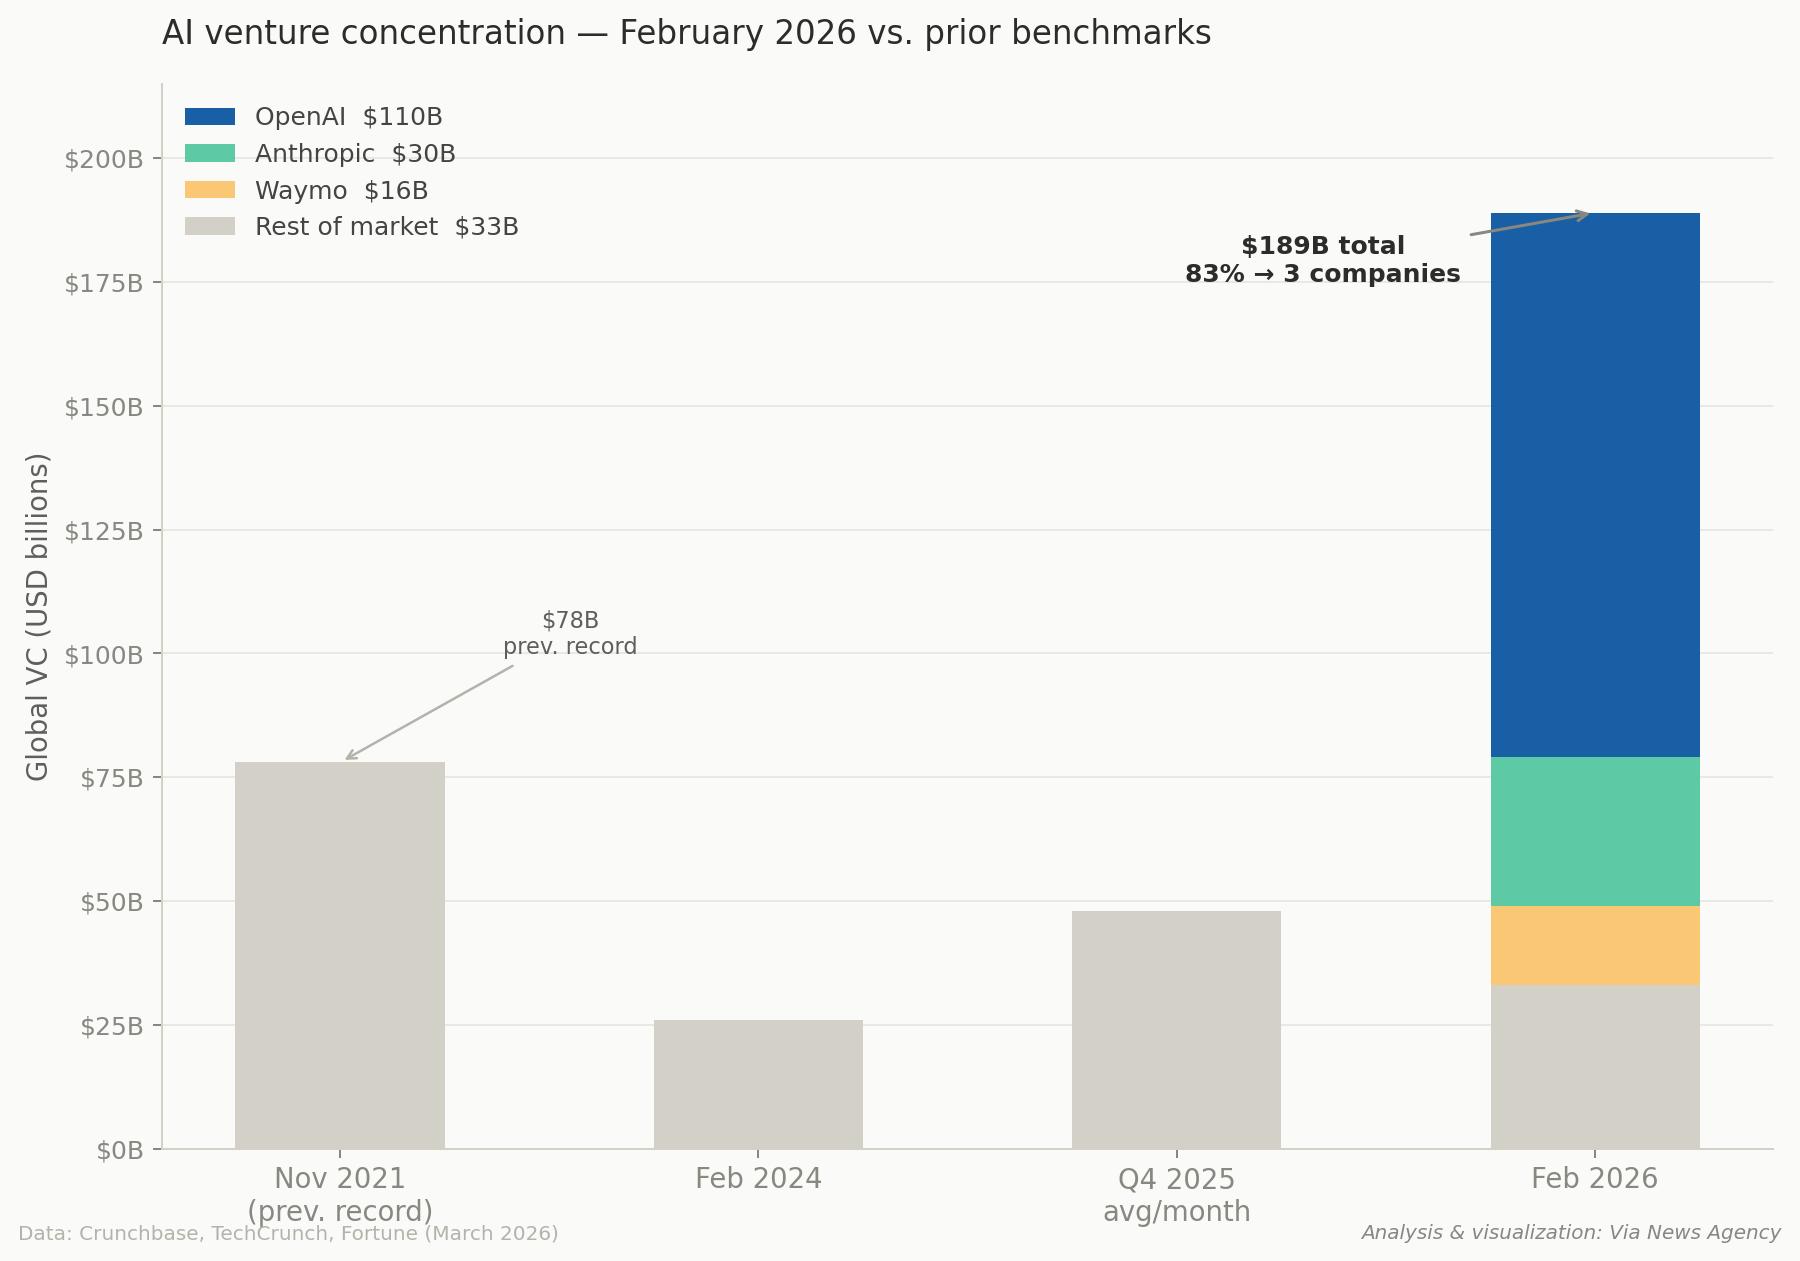
  • OpenAI raised $110B — the largest private venture round in history
  • Anthropic raised $30B — the third-largest ever
  • Waymo raised $16B

Three companies. $156B. 83% of all global VC that month.

The Bifurcation

Now consider the backdrop. The same week those rounds were announced, public markets wiped out $1–2 trillion in software and tech market cap. Investors were fleeing AI-adjacent equities while simultaneously writing the largest private checks in venture history.

That looks like bifurcation.

What the Bubble Narrative Misses

The conventional bubble narrative misses three structural realities:

1. Patient Capital Requirements
R&D cycles now require patient capital that traditional venture timelines can't support — these aren't 5-year exits.

2. Sovereign-Scale Infrastructure
Infrastructure buildouts demand capital at sovereign scale — this looks more like fiber rollout economics than app store speculation.

3. Two-Tier Market Structure
The resulting two-tier market structure may actually reduce systemic risk — concentration at the top keeps the floor stable even as the long tail contracts (seed funding fell 11% YoY in February).

Insurance, Not Speculation

This looks like insurance. Smart money is buying options on not being locked out of critical infrastructure when capital becomes scarce.

Sovereign wealth funds, strategic corporates — they aren't trying to grow fast. They are positioning for the longer term.

Investment Implications

For public market investors, the implication is clear: picks-and-shovels over application layer. Nvidia, cloud providers, and energy infrastructure — not the next SaaS darling.

The bubble framing asks: when does this pop?

The better question: what happens to the countries and companies that didn't buy in and didn't get ready?

AI VC Funding Concentration - February 2026
AI Megaround Funding Concentration - February 2026

About the Chart

November 2021 was the peak of the pandemic-era venture boom. The $78B figure came largely from a cluster of massive late-stage rounds in crypto infrastructure, fintech, and SaaS — spread across hundreds of companies. It was broad-based euphoria.

Why the comparison to Feb 2026 matters:

The 2021 record was diffuse, distributed across many bets in a low-rate, risk-on environment driven by momentum and narrative.

The Feb 2026 record is the opposite: hyper-concentrated, happening during public market volatility, with rates still elevated, and led by strategic/sovereign capital rather than traditional VC.

Same headline number logic, completely different underlying structure.

That's actually the sharpest rebuttal to the bubble comparison. 2021 was a bubble dynamic. Feb 2026 looks more like a directed infrastructure bet.
In this story · Knowledge Files

LM Salvado
LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Agentic AI Goes Operational: Platform Governance, Local Silicon, and the Physical-AI Data Race
In mid-to-late October 2026, enterprise vendors (Cisco, Fortinet, ServiceNow, Intuit, Salesforce/Braze, Adobe) shipped agent governance, AI security and AI-driven customer engagement products, while a parallel hardware wave (NVIDIA RTX Spark laptops, ASUS, Apple's iPad mini, Microsoft's hybrid local/cloud Windows) pushed AI onto local devices. A third strand, physical AI (Encord, Harvest Praxis, Hesai), argues that real-world sensor data and cheaper edge chips are the next bottleneck. The common thread is the shift from AI experimentation to governed, scaled deployment, with Salesforce's Braze acquisition showing consolidation and fintech players like Intuit tying AI to trusted financial data. The facts support a broad industry theme but contain little direct finance or regulatory evidence, so the AI-finance angle is thin.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
Ford Motor Company
Both facts give cash for Ford Motor Company at the same point in time (2025-12-31; FY 2025 year-end and Q4 2025 year-end are the same date). Both are labelled USD, but the values are 23,356,000,000 and 23.356, which cannot both be true in USD. The two numbers agree once the second is read as billions (23.356 bn = 23,356,000,000), so the economic content is consistent and the conflict is a unit/scale error in the Q4 2025 record. The period is not the reason for the conflict: a Q4 and an FY figure at the same year-end date should match.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,995
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,995 facts checked against source5,532 source documents archived
Query this data → isubstrate.com